The gist:
- A manufactured home dealer typically handles inventory selection, pricing, financing coordination, delivery, and site setup in one process.
- Most lots carry multiple factory brands and floor plans so buyers can compare size, price, and layout before ordering.
- Buyers should confirm HUD Code compliance, financing terms, and installation details before signing a purchase agreement.
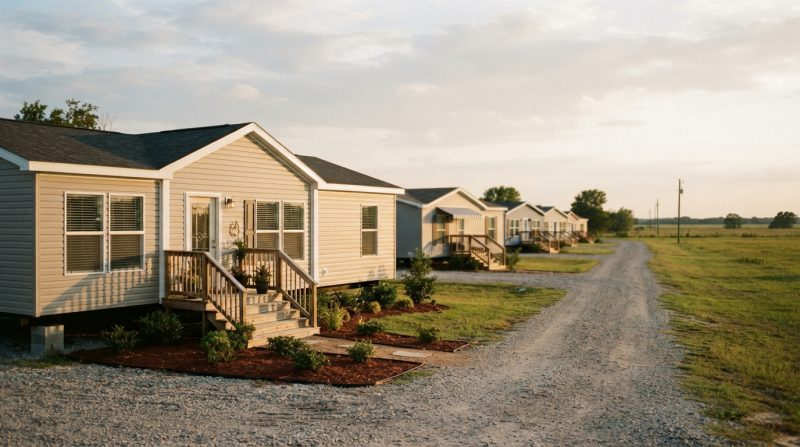
Working with a manufactured home dealer generally means touring an in-stock inventory lot, comparing floor plans from several manufacturers, and arranging financing and delivery through the same business rather than separate contractors.
Shopping with a manufactured home dealer in Sherman, TX usually starts with narrowing down a budget and a general size range before visiting a lot. Dealers typically display model homes on site so buyers can walk through layouts in person rather than relying only on brochures or online renderings. Many lots also offer digital tools such as photos, floor plans, or virtual tours to help buyers shortlist homes before an in-person visit. By exploring these options and comparing available models, you can find your ideal home with Hench’s of Sherman while making a well-informed decision that suits your needs and budget.
Family-owned dealer Hench’s of Sherman has operated in the manufactured housing space since 1983. Based in USA, it serves customers across Sherman, TX, offering a point of comparison for how an established regional dealer structures inventory and services for the area.
What the Buying Process Usually Involves
Most manufactured home purchases move through a predictable sequence, though timelines vary by lender and site readiness.
- Initial consultation to discuss budget, land status, and household needs
- Lot tour to compare display models and available floor plans
- Selection of a specific model, options, and finish package
- Financing application and approval through a lender
- Delivery scheduling, site preparation, and installation
Buyers who already own land typically need utility hookups and a compliant foundation arranged before delivery, while those without land may need to factor lot rent or land purchase into the overall budget.
Comparing Manufactured Home Types
Dealers commonly separate inventory by section count and size, since that affects price, transport logistics, and floor plan options.
| Home Type | Typical Width | Common Use Case |
|---|---|---|
| Single-section | Up to about 18 feet wide | Smaller lots, budget-focused buyers |
| Multi-section (double-wide) | Two sections joined on site | Larger families, more floor plan variety |
| Tiny home | Compact footprint | Buyers prioritizing lower cost and smaller land needs |
Reviewing floor plans by bedroom count, square footage, and price side by side makes it easier to match a model to both household size and site constraints.
Financing, Code Compliance, and Local Considerations
Manufactured homes built after June 15, 1976, must meet federal construction and safety standards known as the HUD Code, which covers structural design, fire safety, and energy efficiency. Buyers pursuing FHA, VA, or USDA financing should confirm the home carries a HUD certification label and data plate, since missing documentation can delay or derail loan approval, according to FHA manufactured home appraisal guidance. Lenders may also require a permanent foundation certification before closing, particularly for federally backed loans.
Buyers in Sherman, TX should also check local permitting requirements and site preparation rules before delivery is scheduled, since setup timelines depend on utility access, soil conditions, and any required inspections. Confirming these details early helps avoid delays once a home is ordered and scheduled for transport.
Frequently Asked Questions
What is the difference between a manufactured home and a mobile home? A manufactured home is built to the federal HUD Code that took effect in 1976, while a mobile home refers to factory-built housing constructed before that standard existed.
Do manufactured home dealers handle delivery and setup? Many dealers coordinate delivery, leveling, and basic utility connection as part of the purchase, though specific inclusions vary by dealer and model.
Can a manufactured home be financed like a traditional house? Financing is available through FHA, VA, USDA, or conventional lenders, but eligibility depends on factors such as HUD Code compliance, foundation type, and whether the buyer owns the land.
How long does it take to move into a new manufactured home? Timelines depend on site readiness and lender processing, since both factory production schedules and local permitting can affect the overall delivery date.
Final Notes
Comparing floor plans, financing terms, and installation details before committing to a specific model helps buyers avoid unexpected costs later in the process. Published details for Hench’s of Sherman cover the service area referenced in this guide.